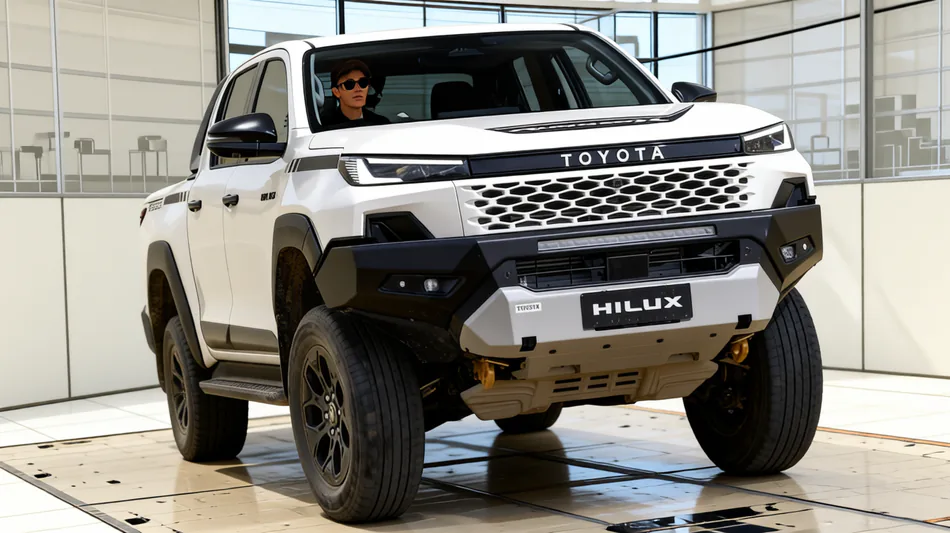
Diesels Reclaim Top Spot in October 2026 as Toyota HiLux Leads Australian Sales
The Toyota HiLux led Australian new-vehicle sales in October 2026 with 5,954 units, marking the first monthly victory for the model this year. Diesel powertrains reclaimed the top spot from electric vehicles, capturing 23.9 percent of the market despite a 14.7 percent volume decline. Total new-vehicle sales rose 6.8 percent to 107,493 units.
The Toyota HiLux has reclaimed the title of Australia’s best-selling individual vehicle for October 2026, ending a period during which electric vehicles held the broader powertrain lead. With 5,954 deliveries, the pickup truck secured its first monthly sales victory of the year, overtaking the Ford Ranger, which recorded 4,841 units.
The HiLux’s performance contributed to a total new-vehicle market of 107,493 units in October, representing a 6.8 percent increase compared to the same month last year. This growth supports a strong year-to-date trajectory, with cumulative sales reaching 1,065,191 units, up 2.5 percent from the first ten months of 2025. Industry analysis suggests 2026 is on track to surpass 2025 as a record year for new-vehicle sales in Australia.
October marked a shift in powertrain dominance, with diesel vehicles reclaiming the top position from electric vehicles (EVs). Diesel sales fell 14.7 percent year-on-year in volume but captured 23.9 percent of the market share, narrowly edging out EVs at 23.1 percent. On a cumulative basis for the year, petrol remains the dominant fuel type with 27.5 percent of total sales, followed by diesel at 24.3 percent and EVs at 19.3 percent.
Toyota maintained its position as Australia’s most popular auto brand in October, with sales rising 4.7 percent year-on-year to 20,649 units. Meanwhile, Chinese manufacturer BYD solidified its status as the second-most popular brand, recording 10,025 units in October alone. This figure represents a 153.2 percent increase year-on-year and extends BYD’s streak of securing second place every month since April.
Competition for the third spot among traditional brands intensified in October. Ford took the position with 7,310 deliveries, despite a 3.4 percent decline in sales compared to the previous year. Kia followed in fourth place with 5,801 units, maintaining a lead over sister brand Hyundai, which sold 4,571 vehicles. Mazda rounded out the top five non-Chinese brands with 5,730 deliveries, a 19.7 percent drop year-on-year.
MG delivered 4,676 vehicles in October, finishing ahead of all other Chinese brands except BYD. This result marked a 31.5 percent increase year-on-year, driven by strong sales of its small hatchbacks and the HS mid-size SUV. However, specific models faced challenges: the ZS small SUV declined by 16.1 percent, and the recently launched U9 ute saw a sharp drop of 61 percent.
The top ten brands list was completed by Hyundai, GWM, Geely, and Chery. Among Chinese manufacturers in the top ten, only GWM experienced a decline, with deliveries falling a modest 0.3 percent to 4,417 units. The broader trend continues to show Chinese brands posting increases while many non-Chinese brands report declines. Several brands, including Cadillac, Mahindra, Smart, and newcomer Lepas, do not currently report sales data to VFACTS or the Electric Vehicle Council.
In the individual model rankings, the Toyota HiLux’s victory was notable as it closed the gap on its arch-rival in year-to-date sales. The Ranger remains slightly ahead overall with 42,699 deliveries compared to the HiLux’s cumulative total. The top five models was completed by the Toyota RAV4 medium SUV with 4,718 units, the Tesla Model Y with 3,105 units, and the BYD Sealion 7 mid-size electric SUV with 2,524 units.
The large SUV segment saw the Toyota Prado outsell its rival, the Ford Everest, with 2,397 deliveries compared to 1,741. Year-to-date, the Prado leads the Everest 18,062 to 17,944. The top ten models list was rounded out by Chinese entries: the Chery Tiggo 4 (2,178 units), BYD Atto 2 (1,943 units), BYD Shark 6 ute (1,843 units), and Geely EX5 mid-size electric SUV (1,789 units). The Ford Everest narrowly missed the top ten, finishing eleventh.
Market segmentation data reveals that SUVs continue to dominate the Australian landscape, holding 62.6 percent of the market share in October. Light commercial vehicles accounted for 20.0 percent, passenger cars for 14.4 percent, and heavy commercial vehicles for 3.0 percent. Medium SUVs were the largest single segment with 31,970 sales, up 23.8 percent year-on-year. Small SUVs followed with 18,756 units, an increase of 12.1 percent.
Sales by fuel type showed diesel leading with 25,649 units, followed closely by electric vehicles at 24,845. Petrol sales totaled 23,605 units, hybrids reached 18,434, and plug-in hybrid electric vehicles (PHEVs) accounted for 11,745 units.
Geographically, New South Wales recorded the highest sales with 30,580 units, followed by Victoria with 28,336 and Queensland with 21,762. Western Australia contributed 11,687 units. All states and territories reported year-on-year growth except for South Australia, which saw a slight decline of 0.5 percent.
Buyer type data indicates that private buyers accounted for 50,876 units, up 5.2 percent year-on-year. Business purchases followed with 40,211 units, an increase of 5.7 percent. Rental fleet sales rose 1.3 percent to 6,469 units, while government purchases declined by 10.9 percent to 2,554 units.
Sales by country of origin highlighted the rapid expansion of Chinese vehicles, which accounted for 41,671 units, a massive increase of 104.2 percent year-on-year. Japanese brands sold 24,089 units, down 13.1 percent. Thai-made vehicles contributed 18,505 units, a decrease of 11.1 percent. Korean brands sold 9,531 units, down 23.5 percent, while German brands accounted for 3,745 units, a decline of 24.0 percent.
The shift in powertrain preference and brand dominance reflects ongoing changes in the Australian automotive market. While electric vehicles have shown strong monthly performance, diesel’s resurgence in October underscores its continued relevance in the national fleet. The close competition between traditional Japanese brands and emerging Chinese manufacturers continues to reshape the top ten rankings, with BYD’s sustained growth posing a significant challenge to established players.
U.Richardson--CT